
 Suleman Chitera
By Suleman Chitera, MFN Reporter
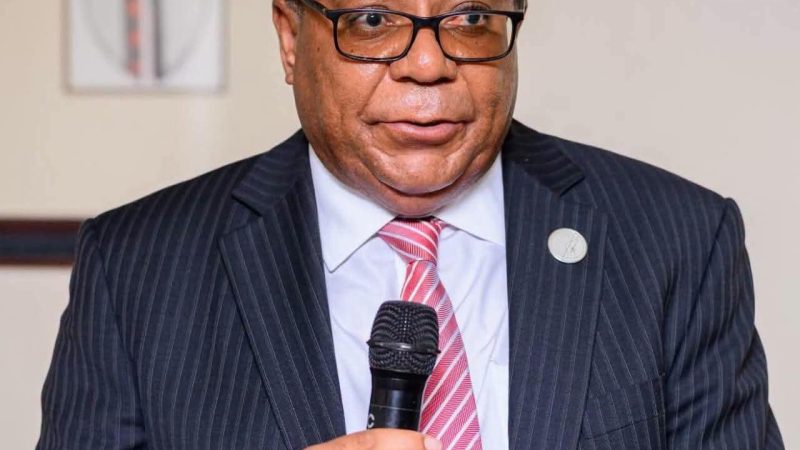
LILONGWE, Malawi — Reserve Bank of Malawi Governor Dr George Partridge has called for stronger cooperation among financial regulators in the Southern African Development Community (SADC) region, warning that the increasingly cross-border nature of financial services requires regulators to work more closely to manage emerging risks.
Partridge made the call on Tuesday in Lilongwe during the 49th Annual General Meeting of the Committee of Insurance, Securities and Non-Banking Financial Authorities (CISNA), a regional platform that brings together regulators responsible for insurance, securities and other non-bank financial services.
He said financial institutions are increasingly expanding their operations beyond national borders, creating regulatory challenges that cannot be effectively addressed by individual countries acting alone.
According to Partridge, closer cooperation among regulators is therefore essential for strengthening financial regulation and supervision across the region.
Cross-border financial activity creates new risks
The Reserve Bank Governor said the growth of cross-border financial activities means that regulators need to improve information-sharing, supervisory cooperation and coordination when responding to risks affecting financial institutions and markets.
He said Malawi and other SADC member states require coordinated, responsive and effective regulatory frameworks capable of keeping pace with developments in the financial sector.
Such cooperation is particularly important for protecting consumers and investors while maintaining confidence in financial markets, he said.
Partridge also called for greater harmonisation of legal and regulatory frameworks across the region.
He said comparable regulatory standards would help ensure that financial institutions, investors, policyholders and pension members receive similar levels of protection regardless of where they operate within the SADC market.
Why regulatory harmonisation matters
The increasing integration of financial markets means that weaknesses in one jurisdiction can potentially create risks beyond national borders.
Harmonised regulatory approaches can make it easier for regulators to supervise institutions operating across multiple countries, exchange information and respond to financial-sector problems before they become wider regional threats.
For consumers, stronger cooperation can also contribute to better protection of savings, investments, insurance policies and pension assets.
The push for harmonisation comes as financial services continue to evolve, with institutions increasingly using technology and expanding their products and operations across borders.
Minister urges stronger protection for consumers
Meanwhile, Minister of Industrialization, Business, Trade and Tourism Simon Itaye called for enhanced regional cooperation in the regulation and supervision of non-bank financial institutions.
Itaye said stronger cooperation is necessary to protect consumers while creating financial systems that can support sustainable economic development.
He said Southern Africa needs resilient, transparent and inclusive financial systems that protect people’s savings, support businesses and mobilise long-term capital for development.
According to the minister, effective regulation of non-bank financial institutions is important because these institutions play a significant role in the financial system by providing services that complement traditional banking.
A stronger regulatory environment, he said, can help build confidence among consumers and investors while creating conditions for greater mobilisation of capital.
CISNA pledges regional cooperation
CISNA Chairperson Kenneth Matomola of Namibia said the organisation remains committed to ensuring that financial institutions across the SADC region move together in strengthening regulatory standards.
Matomola said the regional approach should ensure that no country is left behind as financial markets become increasingly interconnected.
The commitment highlights the importance of cooperation among regulators in addressing regulatory gaps and ensuring that developments in one part of the region do not undermine financial stability elsewhere.
What stronger SADC financial regulation could mean
For Malawi and other SADC economies, stronger cooperation among financial regulators could have several practical benefits, including:
- Better consumer protection: Coordinated supervision can strengthen safeguards for policyholders, pension members, investors and other financial consumers.
- Improved cross-border supervision: Regulators can more effectively monitor financial institutions operating in multiple jurisdictions.
- Faster information-sharing: Cooperation can help regulators identify emerging risks and respond more quickly to problems.
- Greater investor confidence: Consistent regulatory standards can make regional financial markets more predictable and transparent.
- Stronger capital mobilisation: Well-regulated financial markets can help channel long-term savings into businesses and development projects.
- Reduced regulatory gaps: Harmonised laws and standards can reduce opportunities for institutions to exploit differences between national regulatory systems.
The discussions at the CISNA meeting therefore place regional regulatory cooperation at the centre of efforts to build stronger and more inclusive financial markets in Southern Africa.
For Malawi, closer integration with regional regulatory systems could also strengthen the country’s ability to supervise financial institutions with cross-border operations while improving protection for consumers, investors and pension beneficiaries.
As financial markets continue to evolve, Partridge’s call underscores a broader challenge facing regulators across SADC: ensuring that regulation keeps pace with increasingly interconnected financial institutions, markets and consumers.