 Malawi Freedom Network
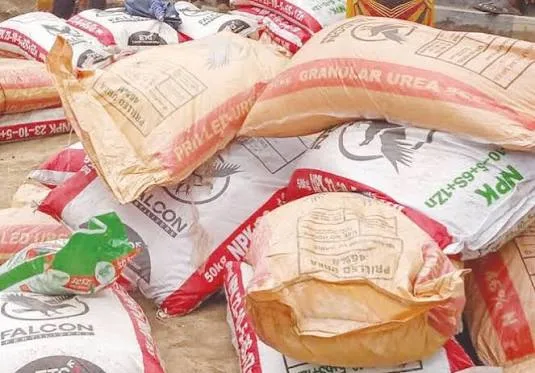
Sealand boss confirmed government payment deal as K11.1 billion FILP programme ballooned into reported K72 billion obligation
By MFN Reporter
The name of businessman Dipak Jevant emerged prominently in one of Malawi’s most controversial fertiliser procurement arrangements after his company, Sealand Investments Limited, became one of four suppliers linked to a reported K72 billion government payment agreement under the Farm Input Loan Programme (FILP).
An investigation published by the Centre for Investigative Journalism Malawi (CIJM) on June 1, 2017, raised serious questions about how a fertiliser programme initially valued at K11.1 billion resulted in a reported payment obligation of K72 billion.
At the centre of the controversy was a financial arrangement involving four suppliers, including Export Trading Company, Sealand Investments Limited, Midima Produce Limited and Bosveld Phosphates.
Jevant, Sealand Investments’ managing director, personally confirmed to CIJM that government had reached an agreement to pay the suppliers through promissory notes.
“They are going to pay us through promissory notes but up to now we have not received it,” Jevant told the investigative journalists.
His confirmation placed Sealand directly within a payment arrangement that raised questions about the calculation of supplier claims, accumulated interest and the financial commitments government had undertaken.
What was Sealand expecting from government?
The most striking revelation in the investigation was that a senior manager from the supplier companies told CIJM that Treasury had indicated it would pay K72 billion, including accumulated profits.
The original FILP programme was valued at K11.1 billion.
That represents a reported difference of approximately K60.9 billion.
The central question is how the suppliers’ financial claims grew to such extraordinary levels and what contractual provisions justified the additional costs.
Sealand’s managing director confirmed the existence of the payment agreement, but his interview did not establish the precise amount payable to his company individually.
That distinction is important because the K72 billion figure concerned the four suppliers collectively, not Sealand alone.
Treasury described the transaction as a mess
Then Secretary to the Treasury Ben Botolo acknowledged that the transaction was extremely complicated.
Botolo said he spent approximately two months trying to understand the arrangements after replacing Ronald Mangani.
He attributed the complications partly to insurance arrangements involving African Trade Insurance and Lloyd’s of London.
He also disclosed that government faced insurance-related obligations, including a reported US$6 million payment to ATI.
However, the explanation left important questions unanswered about the original contracts, interest calculations and the breakdown of liabilities among the four companies.
The questions Dipak Jevant and Sealand must answer
The public interest in this matter goes beyond whether Sealand was entitled to receive payment.
Malawians deserve answers to several fundamental questions:
- What was Sealand Investments’ individual contract value under FILP?
- How much fertiliser did Sealand personally supply?
- How much money did Sealand claim from government?
- What interest or additional charges were included in its payment claim?
- What contractual provisions justified those additional costs?
- How much did Sealand eventually receive, and when?
- Can the company provide documentary evidence supporting its claims?
These questions are necessary to establish whether the payment arrangement was commercially and legally justified.
Public accountability cannot be optional
The FILP controversy exposed serious weaknesses in the management of public procurement, supplier financing and government financial commitments.
While suppliers may have legitimate contractual claims against government, public authorities must demonstrate that every payment is supported by valid contracts, verified deliveries and properly calculated obligations.
Jevant’s confirmation of the payment agreement makes Sealand an important part of the story that deserves further scrutiny.
The question is not whether a businessman should be paid for goods legitimately supplied.
The question is whether Malawians were expected to carry an enormous financial burden without a sufficiently transparent explanation of how the liabilities were calculated and approved.
Malawians deserve the full FILP payment breakdown. Sealand Investments and the relevant government institutions should provide answers.